Legislative position on 28 October 2026: the measures discussed here form part of a bill submitted to Parliament. They are not enacted law. Parliament records submission on 26 October and a meeting of the competent committee on 29 October 2026.
When an estate contains cryptoassets, the first difficulty is often practical: how can they be located, and who can lawfully gain access? Greece’s new tax bill asks a different question: how should these assets fit into property-tax rules? Its answer requires careful reading. A classification adopted for a specific tax purpose does not automatically resolve ownership, succession or international jurisdiction.
Three points to retain
- Articles 51–53 propose specific rules for cryptoassets passing through inheritance, gifts and parental transfers.
- The classification as movable property abroad concerns this particular tax framework. It does not itself create an exemption from Greek tax.
- The proposed valuation date is the day before the tax liability arises, which is not necessarily the day before every death.
What the submitted text actually proposes
Article 51 would add paragraph 5 to Article 55 of the Property Tax Code, Law 5219/2025. For the relevant tax provisions, cryptoassets would be treated as intangible movable property abroad. Article 52 would introduce Article 62A on valuation, while Article 53 would add paragraph 3 to Article 89 concerning gifts and parental transfers. These are the numbers in the submitted bill; they should not be confused with earlier consultation numbering.
Assigning a tax category makes it easier to apply rules to an asset without an obvious physical location. It does not imply that a particular computer or country has been identified as the place where every Bitcoin resides. It is a legislative choice with a defined purpose. Further legal analysis would be needed before drawing conclusions about the law governing succession or the court with jurisdiction.
Why “abroad” does not mean tax-exempt
Inheritance tax can already extend to movable property abroad where the statutory connecting factors apply, as the Greek tax authority, AADE, explains. The proposed classification therefore does not support a general conclusion that inherited cryptoassets fall outside Greek taxation. Whether tax applies, whether an exemption is available and how the amount is calculated are separate questions.
Keeping those stages distinct is useful for readers. First identify the property right being transferred and its recipient. Then examine the conditions for taxation in Greece, followed by valuation and the relevant calculation rules. The expression “property abroad” replaces none of these steps and cannot, by itself, determine an individual tax outcome.
Which valuation date matters?
Proposed Article 62A links valuation to recognised platforms and a euro value on the day before the tax liability arises. The time reference matters for assets whose market price can move sharply. It should not casually be replaced by the acquisition price, a later sale price or the balance displayed when somebody begins preparing the tax return.
The date on which the tax liability arises must first be established under the rules applicable to the particular situation. It is not invariably the date of death. Useful preparation therefore includes dated records of quantities and prices, together with a clear account of their source. The bill does not justify choosing a convenient date or platform retrospectively without explaining the method used.
From a digital wallet to an inheritance share
Technical control of a wallet, ownership of the assets and entitlement as an heir are different concepts. Access information establishes a technical ability in the first instance, rather than the entire legal relationship. Equally, knowing a public address does not by itself connect every asset displayed at that address with a particular person and estate.
The proposed tax classification does not remove the need for that evidence. Preparing a file may require provider records, transaction histories and documents explaining the person’s relationship with the cryptoassets. The distinction also helps people arranging their affairs in advance: secure access planning and the legal and tax documentation of a transfer perform different functions.
What records are worth retaining?
A readable record can identify the type and quantity of cryptoasset, relevant public addresses, transaction identifiers and available account statements. It should also explain where the valuation comes from and the date to which it relates. The purpose is verification, rather than accumulating unrelated personal information.
Private keys, recovery phrases and passwords need separate, secure handling. They should not be placed in shared documents or sent as part of an ordinary request for information. An organised file can describe the existence and origin of property without indiscriminately disclosing the mechanism that would enable someone to move it.
Gifts, parental transfers and commencement
Article 53’s treatment of gifts and parental transfers shows that the proposal extends beyond transfers on death. It does not mean that every movement between two addresses is necessarily a gift. Classification depends on the underlying legal relationship, the beneficiary and the reason for the movement. The technical entry on a network cannot answer all these questions by itself.
Article 390 paragraph 3 of the submitted text proposes application to tax liabilities arising from 1 January 2027 onwards. That provision must be checked against the final legislation if the bill is passed. Until then, a proposed date should not be presented as an established obligation, nor should it displace a separate assessment of earlier events.
The significance of the proposal
The important development is an attempt to connect digital property with workable tax rules. A decentralised technical system does not eliminate the need for legal concepts, but it requires precision about the purpose for which they are used. The useful question is not an attention-grabbing universal answer to where Bitcoin is located. It is whether the law provides an applicable rule with clear limits and a verifiable valuation.
For citizens and legal practitioners, the practical lesson is to organise evidence while keeping access, ownership and tax treatment separate. Parliamentary scrutiny will establish whether the proposals are adopted and in what final form. Responsible reporting should follow that process without attributing legal effects to a bill that it does not yet possess.
Primary sources
Hellenic Parliament: submission date and legislative status · Submitted bill: Articles 51–53 and 390§3, PDF pages 64 and 427 · AADE: general inheritance-tax framework. Sources checked: 28 October 2026.
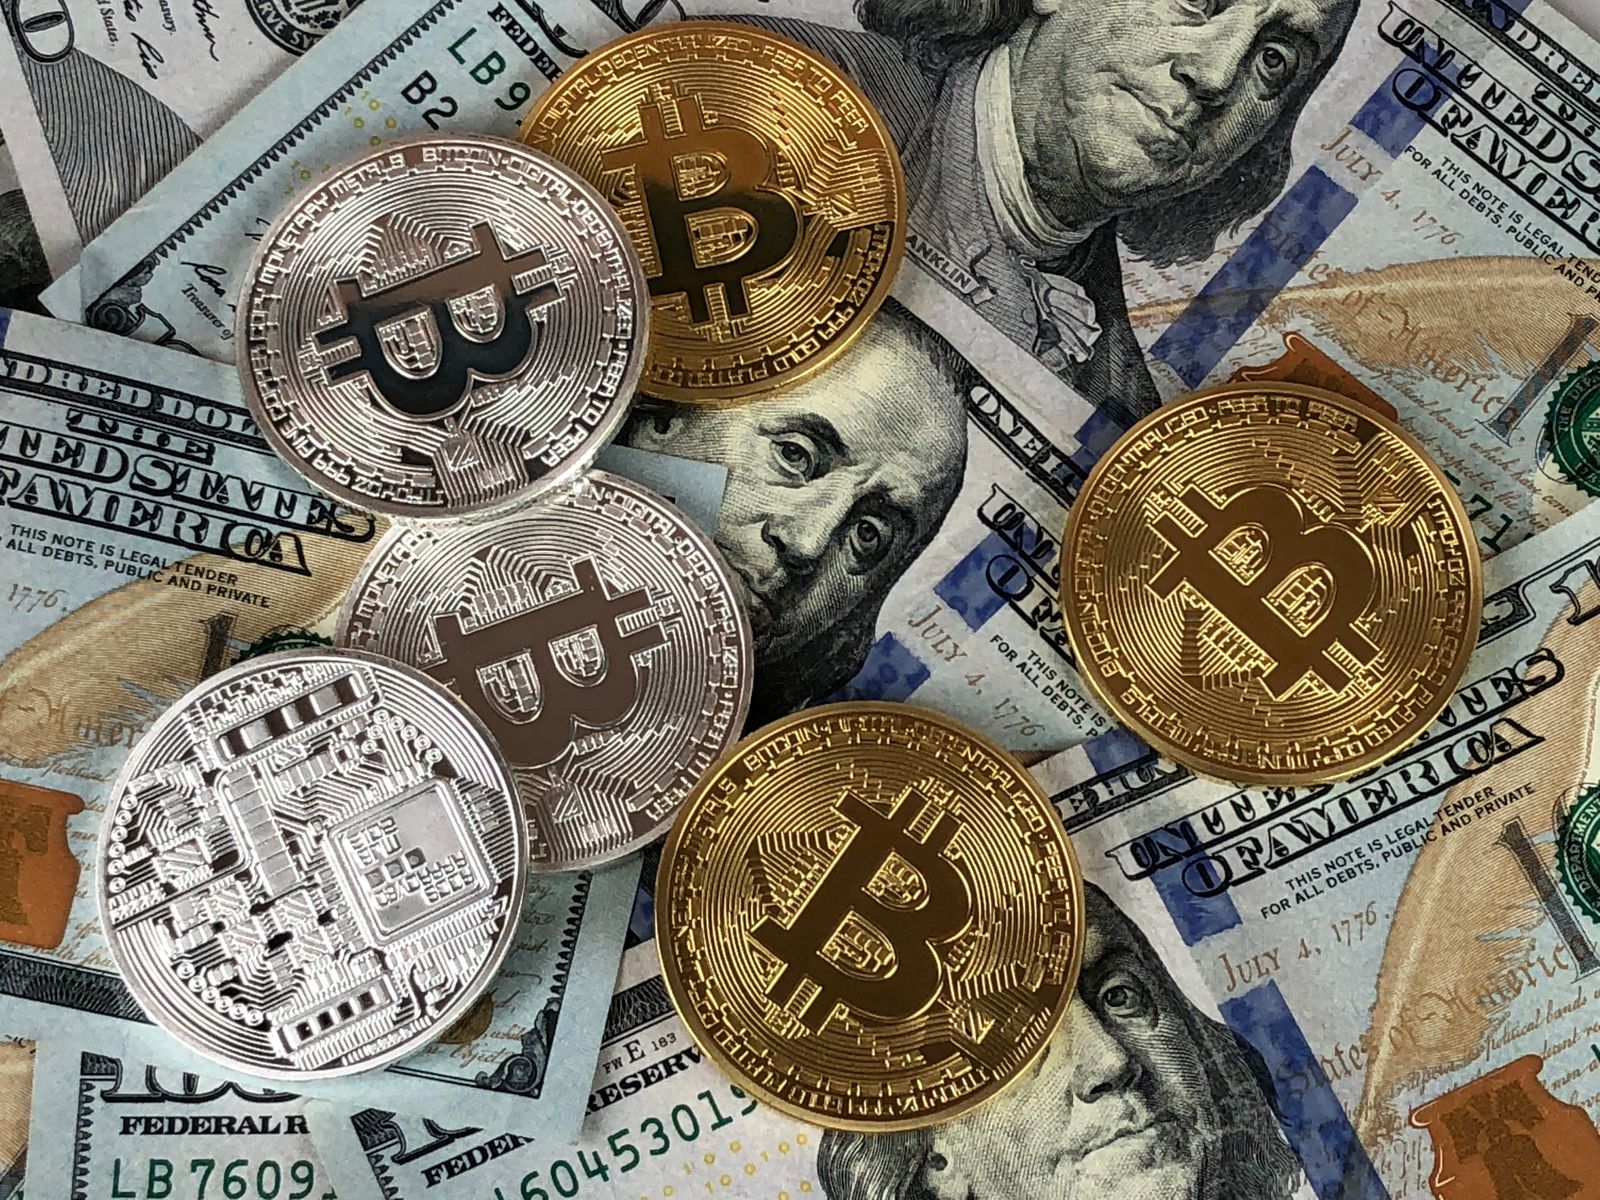
Illustrative photograph of cryptoassets. Photograph: David McBee / Pexels.
Comments
Share your thoughts about this article.
No comments yet. Be the first to comment.
Submit a comment